Short answer: most homeowners ask for a licence number and proof of insurance, receive both, and are still exposed. A licence number proves somebody registered. An insurance PDF emailed by the contractor proves what their policy looked like on the day they saved that file, which may have been two years ago.
Seven stages below, spread across the hiring process rather than done in one sitting. Two of them matter more than the rest: getting the certificate of insurance from the insurer with your name on it, and getting a lien waiver every time you pay. Those two are the difference between checking and actually being protected.
There is a printable checklist at the end covering all seven.
Before you call anyone, write down the job
Every stage below depends on this one, and it takes ten minutes.
Write down what you want done, what you are specifically not asking for, any materials you have already chosen, your timeline, and your rough budget. Vague scope is the single biggest cause of disputed change orders later, because "we assumed that was included" is an argument nobody wins six weeks into a build.
One practical point while you are arranging visits. A contractor who gives you a price without seeing the site is not estimating, they are guessing. Wisconsin's consumer protection agency specifically recommends getting estimates from contractors who come and look at the job, and it is good advice everywhere.
Stage 1: The five-minute screen
Before you spend any more time on someone, confirm three things.
The business is registered. Search your state's business registry and check the entity exists under the name they gave you, with an active status.
The licence is current. Most states require a licence for major remodelling work, and requirements vary by state and by trade. Search the licence number rather than the business name if you have it, since numbers are harder to fudge.
The licence belongs to the people doing your work. A number registered to someone who will not be on site is worth asking about.
The liability point is worth knowing before you skip this. Using an unlicensed contractor in a state that requires one can leave you exposed, not just them.
This is the same groundwork covered in our guide to checking whether a business is legitimate, which walks through the registry and licence lookups in detail, including how to spot the paid lookalike sites that crowd the search results when you go looking for your state's official registry. If a contractor fails this stage, nothing below matters.
Stage 2: Verify the insurance properly
This is the stage most people think they have done and have not.
Two policies matter. General liability covers damage to your property. Workers' compensation matters because without it, a worker injured on your property can become your financial problem rather than their employer's.
Now the part that separates a real check from a formality.
Do not accept a PDF the contractor emails you. Ask them to have their insurance agent or broker send you a certificate of insurance directly, with your name and address listed as the certificate holder. Wisconsin's consumer protection guidance recommends exactly this, and it is the single most useful sentence in this article.
The reason is mechanical rather than suspicious. A certificate the contractor forwards you is a snapshot of one day, and policies lapse, get cancelled for non-payment, or quietly expire mid-project. A certificate naming you as holder means the insurer contacts you if the policy stops. You find out in a letter rather than after an accident.
Two more things to check on the certificate when it arrives. The coverage dates should run past your expected completion date, and the policy limits should be sensible against the value of the work. A $50,000 liability limit on a $200,000 renovation is not really coverage.
Stage 3: References that tell you something
Everyone asks for references. Almost nobody learns anything from them, because no contractor hands over the number of a customer who hated them.
The fix is in what you ask for and what you ask.
Ask for recent, similar work. Customers from the last year, with projects comparable in scope to yours. A glowing reference from a small repair in 2019 tells you nothing about how they handle a kitchen.
Then ask questions that cannot be answered with "they were great."
- What went wrong, and how did they handle it?
- Did the final price match the estimate? If not, why?
- Did the crew turn up when they said they would?
- Would you use them again for a bigger job?
That last question does the most work. Plenty of people will say they were satisfied. Far fewer will commit to hiring someone again for something larger, and the hesitation in that answer tells you more than the answer itself.
Stage 4: Reading the estimate
Get at least three, and make sure all three are quoting the same scope. Otherwise you are not comparing prices, you are comparing different jobs.
A usable estimate contains:
- Itemised labour and materials, separately
- Brand and model for significant materials, not "or similar"
- Allowances stated explicitly, with what happens if you exceed them
- Start and completion dates
- What is specifically excluded
Now the honest counterweight to the advice everyone gives about getting three quotes. Kiplinger, citing Consumers' Checkbook data, reported estimates for the same job ranging from $113,000 to $205,000, and from $26,000 to $61,000 on another.
A spread that wide almost never means one contractor is cheating you. It usually means they are pricing different work, with different materials and different assumptions about what is included. The low bid is frequently the one that left something out, and you will meet that omission later as a change order.
Read the cheapest quote looking for what is missing, not for what is cheap.
Stage 5: The contract
The FTC's guidance on avoiding home improvement scams sets out what belongs in a written contract, and it is worth following line by line.
- Contractor's name and physical address, not just a PO box
- Full description of the work and the materials
- Total price, including any finance charges
- Start and completion dates
- Warranty terms and what the warranty excludes
- A written statement of your right to cancel within three business days
That last item is one almost no homeowner knows about. Wisconsin's guidance on home improvement contracts gives the mechanics for that state: three business days to cancel a contract over $25 signed at your home, with any unexpended funds returned within 15 days. The details vary by state, so check your own, but the right generally exists in some form.
One more FTC warning worth its own line. Be careful with financing the contractor arranges for you. Homeowners have signed up to high-interest home equity loans through a contractor without fully understanding that they had just put their house up as security for a kitchen.
If a contractor will not put the job in writing, that is the end of the conversation. Wisconsin's guidance is blunt about it: do not rely on oral agreements.
Stage 6: Payments and deposits
Never pay the full cost upfront. The FTC notes that many states limit how much a contractor can legally ask for as a down payment, which is worth knowing exists even if you do not know your own state's number. Search "[your state] contractor down payment limit" before you agree to anything.
Structure the rest in three parts:
A reasonable deposit to cover materials and secure the slot.
Progress payments tied to completed milestones, not to dates on a calendar. "When the rough-in passes inspection" is a milestone. "On the 15th" is not, and it means you can end up fully paid up on work that has not happened.
A final payment held back until the work is finished and you are satisfied with it. The FTC is explicit on this point.
Payment method matters too. Cash-only requests are a red flag the FTC names specifically, and cards and cheques create a record you may need later.
Stage 7: Lien waivers
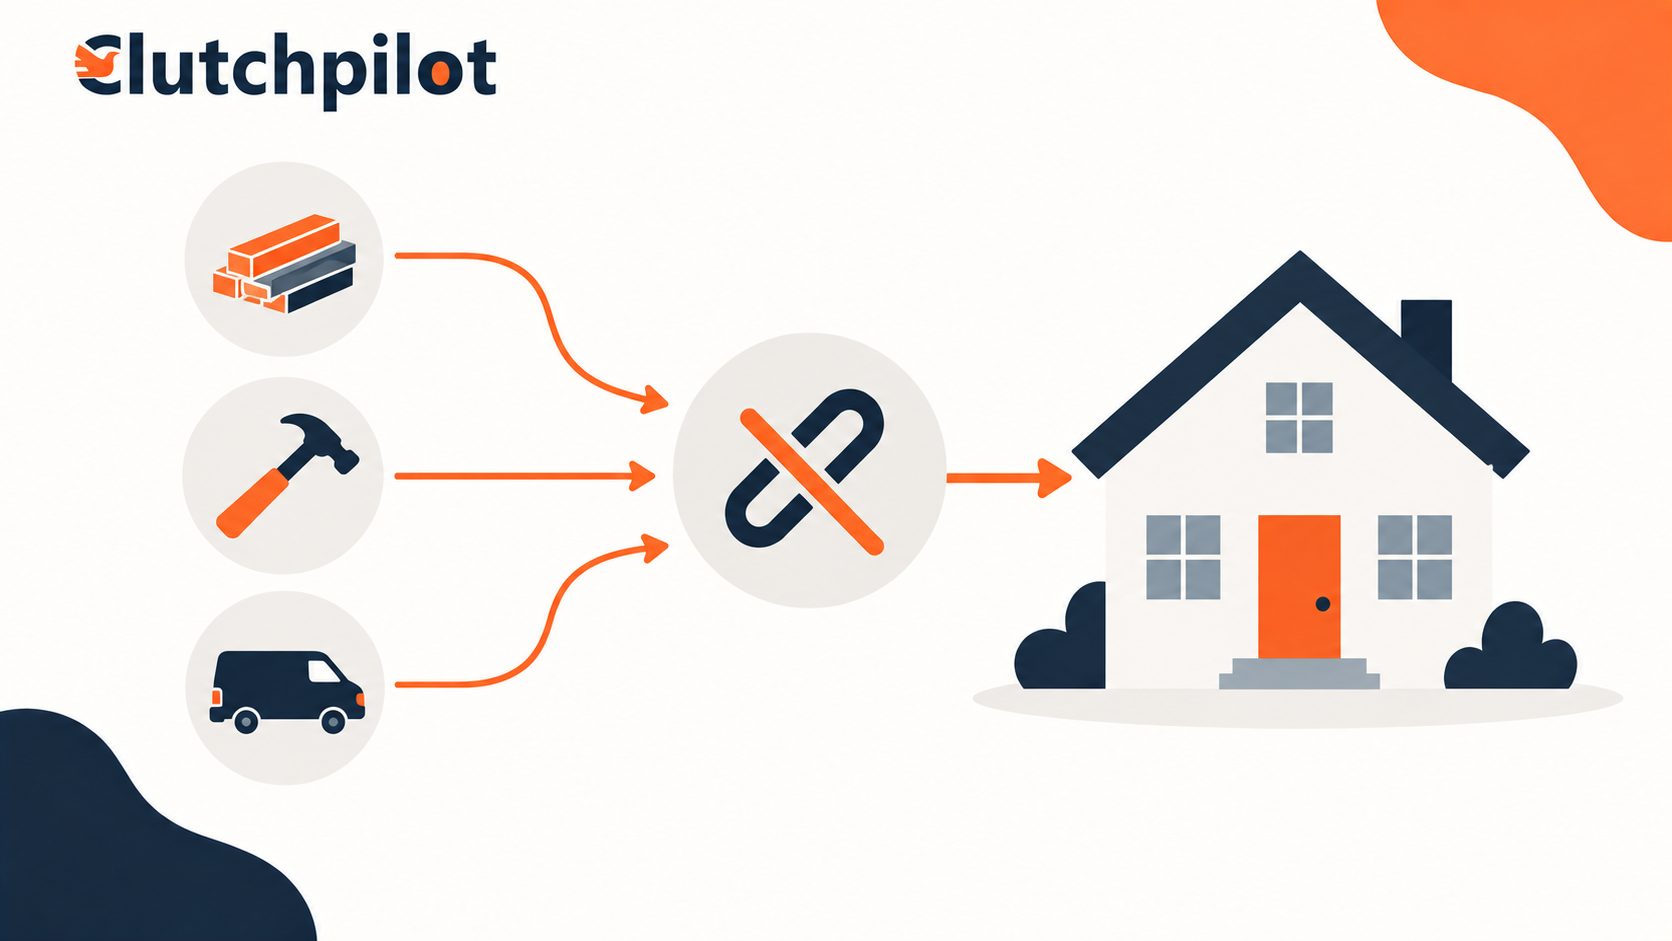
This is the risk almost nobody knows about, and it is the one that can cost you the most.
If your contractor does not pay their suppliers or subcontractors, those suppliers and subs can place a mechanic's lien against your property. Even if you paid the contractor in full. Even if you have receipts. The lien attaches to the house, and you can end up paying twice for the same materials.
The protection is simple and most homeowners never ask for it. Request a lien waiver at the time of each payment, and especially at final payment. Wisconsin's guidance states that contractors must provide them on request.
A lien waiver is a document in which the contractor, or the supplier, confirms they have been paid and gives up their right to lien your property for that work. Terminology varies by state, and there are conditional and unconditional versions, which differ in whether the waiver takes effect immediately or only once the payment clears. Ask which you are getting.
If a contractor is uncomfortable providing lien waivers, that reaction is itself useful information about whether their suppliers are being paid.
Red flags
Mostly drawn from the FTC, which keeps this list sourced rather than anecdotal.
- They knocked on your door. Not automatically fraud, but it is the circumstance in which most of it happens, particularly after a storm.
- They have materials left over from another job. A specific and long-running pitch the FTC names.
- Pressure for an immediate decision. A price that expires tonight is a sales tactic, not a price.
- Full payment upfront, or cash only.
- No physical address. A mobile number and a PO box give you nowhere to go if something fails.
- Reluctance to put anything in writing.
- A bid far below the others with no explanation. Ask what is excluded before assuming you found a bargain.
The printable checklist
Print this and take it to the site visit. It follows the seven stages above.
Stage 1: Screen
- Business found in state registry, status active
- Licence number verified with the state board
- Licence current and held by whoever is doing the work
- Trading under this name for a plausible length of time
Stage 2: Insurance
- General liability confirmed
- Workers' compensation confirmed
- Certificate of insurance sent by the insurer or broker, not the contractor
- My name and address listed as certificate holder
- Coverage dates run past my completion date
- Policy limits sensible for the value of the work
Stage 3: References
- Two or more references from the past year
- Projects similar in scope to mine
- Asked what went wrong and how it was handled
- Asked whether the final price matched the estimate
- Asked whether they would use them again for a bigger job
Stage 4: Estimate
- Three estimates, all quoting the same scope
- Labour and materials itemised separately
- Brands and models named for significant materials
- Allowances stated, with overage terms
- Exclusions listed
- Checked the low bid for what is missing
Stage 5: Contract
- Physical address, not just a PO box
- Full description of work and materials
- Total price including finance charges
- Start and completion dates
- Warranty terms and exclusions
- Right to cancel stated in writing
- No contractor-arranged financing signed without independent advice
Stage 6: Payments
- Checked my state's down payment limit
- Deposit is reasonable, not the full amount
- Progress payments tied to milestones, not dates
- Final payment held until work is complete and satisfactory
- Paying by a method that leaves a record
Stage 7: Liens
- Lien waiver requested at each payment
- Lien waiver obtained at final payment
- Clear on whether waivers are conditional or unconditional
If you do nothing else
Two things carry most of the protection.
Get the certificate of insurance from the insurer, with your own name on it as certificate holder, so you hear about it if the policy lapses.
Get a lien waiver at final payment, so a supplier you have never met cannot attach a claim to your house.
Everything else on the checklist is worth doing. Those two are worth doing even when you are in a hurry.
Comments (0)